WASHINGTON, D.C. — June 2026 — Buyers who purchase, title or finance vehicles through limited liability companies (LLCs) are navigating an evolved environment created by the Financial Crimes Enforcement Network’s (FinCEN) beneficial‑ownership information (BOI) reporting obligations under the Corporate Transparency Act (CTA). The requirement still does not prohibit LLC ownership, but as of June 2026 it is reshaping timing, documentation and privacy expectations for high‑value and collectible car transactions nationwide.
Why this matters now
FinCEN began accepting BOI filings on January 1, 2024; the practical fallout has continued to accumulate. Dealers, lenders and specialty insurers report that what began as sporadic surprises in 2024–25 is now routine process management in 2026. For buyers of six‑figure sports cars, limited‑run exotics and collector vehicles, the principal friction points are delivery timetables, underwriting verifications and state titling windows—areas where unexpected paperwork can translate to lost allocation slots and added expense.
What the BOI rule still requires
The basics remain: most state‑filed corporations and LLCs are “reporting companies” unless they meet a statutory exemption. A BOI report must include the company’s legal name, trade names, current address, jurisdiction of formation and taxpayer identification number, plus identifying information for each beneficial owner and individuals exercising substantial control. Identification requires name, date of birth, residential address and an identifying document number (for example, passport or driver’s license) with an image.
FinCEN continues to offer FinCEN identifiers as a privacy and operational convenience. Many buyers and corporate‑formation providers rely on those identifiers to avoid repeatedly submitting sensitive ID images across multiple transactions and filings.
What’s changed since March 2026
- Operational standardization at dealerships: Larger specialty dealers and consignors now include FinCEN identifier fields in their entity purchase packets and require BOI status confirmation early in the sale process. That shift reduces last‑minute holdups that formerly delayed delivery by days or weeks.
- Underwriting clarity from specialty insurers: Several national specialty insurers that underwrite collectible and high‑net‑worth auto policies have publicly updated their underwriting checklists to note acceptable entity documentation and garaging disclosures. Expect more explicit policy language that ties insurability to verified BOI filings or a FinCEN identifier.
- Lenders tightening procedural checks: While commercial underwriting practices vary, an increasing number of captive finance arms and private lenders now request evidence of an entity’s BOI filing or a FinCEN identifier before releasing funds on entity‑titled vehicles.
- Formation services and DMS integration: Formation companies increasingly offer bundled BOI filing (including expedited FinCEN‑identifier requests). In parallel, dealer management systems and title service platforms have begun adding fields to capture FinCEN identifiers and flag incomplete BOI statuses for title clerks.
How transactions are adapting in real terms
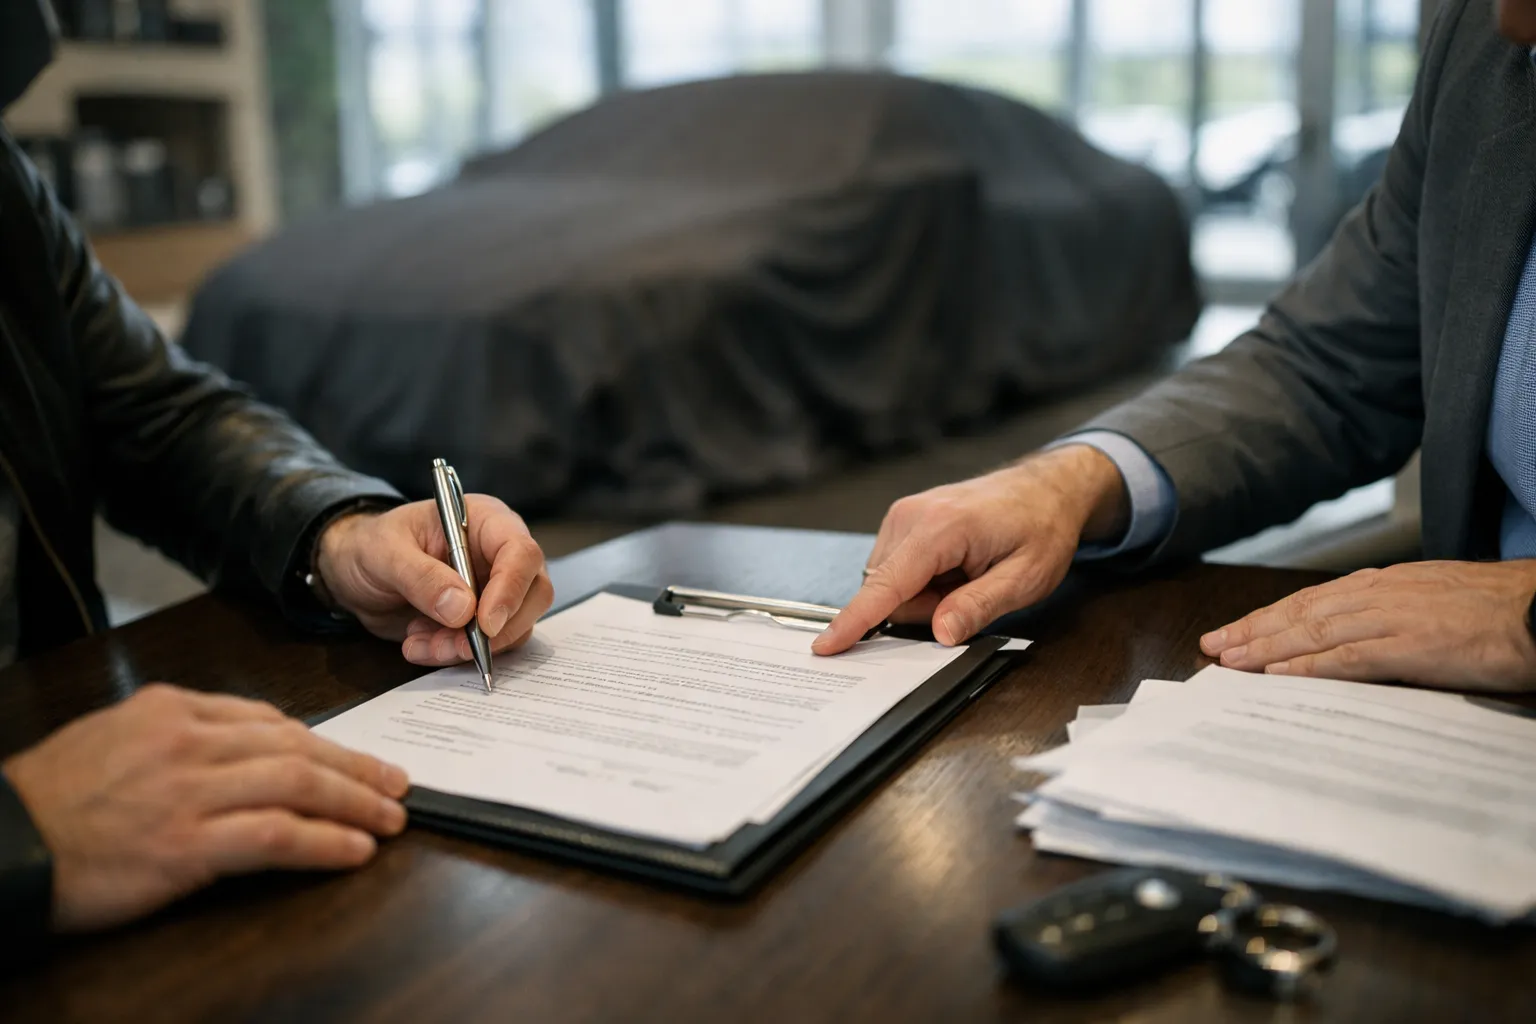
From interviews with dealers in New York, Los Angeles and Miami, the common practice now is to treat entity purchases as small commercial transactions: deposits are taken only after the entity formation and BOI filing are underway; certified operating agreements or corporate resolutions naming the authorized signer are required up front; and escrow or dealer‑held funds are sometimes conditioned on proof of BOI filing.
Examples from the field:
- A Manhattan dealer told me that, in May 2026, two limited‑allocation hypercar deliveries were rescheduled when buyers formed LLCs days before expected delivery and had not provided FinCEN identifiers or filing confirmations.
- A Florida title service now requires confirmation of BOI status before accepting an out‑of‑state entity for a same‑day title transfer—a change that prevents regressive trips to the DMV but can add a 48–72 hour wait if filings are incomplete.
Impact: who is affected and how
The effects cluster into three practical areas:
- Timing and delivery risk: Buyers forming LLCs near allocation or delivery dates risk postponements while lenders, insurers and title agents verify BOI filings.
- Operational costs: Expect modest additional expense—expedited BOI filing fees, formation‑service premiums, notary and certified‑document charges—and potential loss of limited allocations if delivery slips.
- Privacy expectations: BOI information is not public, but it becomes a federal record accessible to authorized government users and, for permitted purposes, certain financial institutions. Buyers expecting absolute obscurity should reassess their plans.
What stakeholders are saying
FinCEN’s public materials remain the official source for filing requirements and acceptable documentation; the agency’s BOI reporting portal is the route for filings. Dealers and title professionals say the rule has encouraged earlier triage of entity purchases rather than discouraging them. Specialty insurers that spoke with Car Buying Guide emphasize that transparency about garaging and use is the main underwriting concern—not ownership per se.
“Plan earlier and make the BOI status part of your deposit conversation,” one dealership general manager in Los Angeles advised. “It’s not a showstopper, but it’s a scheduling problem if you wait.”
Updated, practical steps for June 2026 buyers
- Form the LLC and file BOI before placing a deposit: if you intend to title a vehicle to a new entity, establish the LLC and file the BOI report—or at minimum request a FinCEN identifier—well before allocating funds on limited‑availability cars.
- Include the FinCEN identifier in your purchase packet: provide the identifier or filing confirmation to the dealer, lender and title company at the outset to reduce redundant requests for ID images.
- Prepare certified corporate documents: have a signed operating agreement or certified resolution identifying the authorized purchaser and any signer for the title/finance documents.
- Confirm insurer acceptance early: ask your broker or underwriter whether they require a BOI filing confirmation or a FinCEN identifier as a condition of binding entity‑titled coverage and ensure garaging addresses match the LLC records.
- Budget for administrative lead time: add 3–7 business days for formation and filing if you are not using an expedited service—plan longer for cross‑border or international ID documents.
- Consult counsel for structure decisions: if privacy or tax optimization is a priority, discuss trusts and other ownership forms with a qualified attorney and tax advisor; these alternatives carry distinct titling and underwriting consequences.
What’s next to watch in late 2026
- Further standardization from dealer networks and finance providers on what constitutes acceptable BOI evidence for funding and titling.
- Broader adoption of FinCEN identifiers among repeat buyers and formation-service clients to minimize repeated ID submissions.
- State titling offices and private title vendors refining workflows and, potentially, producing state‑specific checklists for entity titling tied to BOI expectations.
- Legal and legislative activity that could clarify access rules or exemptions—buyers should monitor FinCEN guidance pages and consult counsel for major transactions.
FAQ: BOI reporting and buying a car through an LLC (June 2026)
Does BOI reporting make my LLC car ownership public?
No. FinCEN’s BOI database is not a public registry. Access is restricted to authorized government users and, for permitted purposes, certain financial institutions. However, the information is a federal record and can be disclosed to authorized entities; it is not the same as anonymity in state registries or third‑party title searches.
If my LLC already exists, what should I check before closing a purchase?
Confirm that your LLC has filed its initial BOI report and that the report reflects current beneficial owners and authorized signers. If you’ve changed addresses, added owners or updated control persons, update the BOI report before closing to avoid underwriting or title delays.
Will a dealership require my BOI report to complete a sale?
Most dealers will not demand the BOI filing itself, but entity transactions commonly trigger requests for operating agreements, certified resolutions and authenticated IDs. Some lenders, insurers and title services may ask for a FinCEN identifier or filing confirmation as part of their due diligence.
Is it still worthwhile to title a luxury car to an LLC?
Yes—LLCs remain a useful tool for liability planning, fleet management and multi‑driver households. The difference in 2026 is operational: successful entity titling requires planning the entity formation and BOI filing into the purchase timeline to avoid inconvenience and preserve limited allocations.
Where can I verify current BOI filing rules and deadlines?
Start with FinCEN’s BOI reporting portal and the agency’s official FAQs for the latest filing windows, acceptable identification documents and guidance on FinCEN identifiers. For state‑specific titling rules and tax implications, consult the relevant state motor vehicle department and a qualified attorney or tax advisor.