WASHINGTON, D.C., June 24, 2026 — The Federal Trade Commission’s Combating Auto Retail Scams (CARS) Rule remains stayed while litigation continues, leaving U.S. car buyers to navigate a patchwork of federal statutes, state consumer‑protection laws and marketplace practices. Who this affects: every consumer—especially luxury buyers—who expects clear, itemized out‑the‑door pricing and certainty about recurring services bundled into a vehicle deal. What to do now: demand written, itemized buyer’s orders that name lenders, list recurring charges with totals over term, and confirm software/feature transferability. When and where: immediately, at showrooms and online checkout flows nationwide. Why it matters: dealers and OEMs are increasingly packaging subscription services, telematics and software features that can add hundreds or thousands to lifetime ownership costs.
Context: what the stayed CARS Rule sought to change
The CARS Rule, finalized in 2023, sought to require express, informed opt‑in for dealer add‑ons, tighten advertised‑price and monthly‑payment disclosures, and make consent a clear, documentable act. Because the rule is stayed, those uniform national mandates are not yet enforceable as a standalone regime. That does not leave buyers without protection: the FTC retains authority under Section 5 of the FTC Act to pursue deception, the Truth in Lending Act (TILA) and Regulation Z cover key financing disclosures, and state unfair‑and‑deceptive‑acts statutes (UDAP) and state motor‑vehicle laws remain active enforcement tools.
What has changed since March 2026: fresh trends buyers must watch
- Rise of software and telematics subscriptions. Beyond traditional F&I products, OEMs and dealers increasingly sell recurring services—connected navigation, advanced driver assistance as a subscription, remote concierge, and theft‑recovery telematics. A $15–$35/month fee compounds over ownership and may not be transferable or cancelable without a dealer intervention.
- More of the deal happens electronically. Full online checkout and one‑click finance options are common. That can improve transparency if the configurator shows taxes, titling and dealer fees — but many digital flows still use placeholders or “estimate” language that later becomes binding at signing.
- Trade‑in uncertainty shifted online. Instant online appraisals are useful but often conditional on in‑person inspection; buyers should treat online numbers as provisional until written into the buyer’s order.
- State enforcement remains the most active lever. Where federal rulemaking is paused, state attorneys general and consumer bureaus are issuing guidance and bringing suits under state law; outcomes will continue to vary by jurisdiction.
Details that cost you money — updated June 2026
Luxury purchasers feel these shifts acutely because software and subscription features are more likely to be marketed as premium, ongoing services. Key vectors for hidden cost:
1) Recurring software and telematics fees
Example: a $25/month connected‑services fee over 60 months equals $1,500. Add that to a $2,500 dealer protection package financed at dealer APR and the total lifts the lifetime cost materially. Ask for the cumulative cost, cancellation terms, and whether services transfer with resale.
2) Non‑transferable safety or driver‑assist features
Some OEMs offer feature subscriptions tied to the original buyer; subsequent owners may lose access unless a separate license is purchased. For expensive features (adaptive cruise, hands‑free driving), confirm transferability in writing before paying.
3) Financing markups and brokered loans
Dealers can still mark up lender rates where state law permits. If a lender is named, request written verification of the lender’s base rate and whether there was any dealer markup; bring a bank pre‑approval to anchor negotiations.
June 2026 playbook: exact documents and questions to demand
Refine the buyer’s checklist for both showrooms and digital checkouts. Insist you receive these items before authorizing a credit pull or signing:
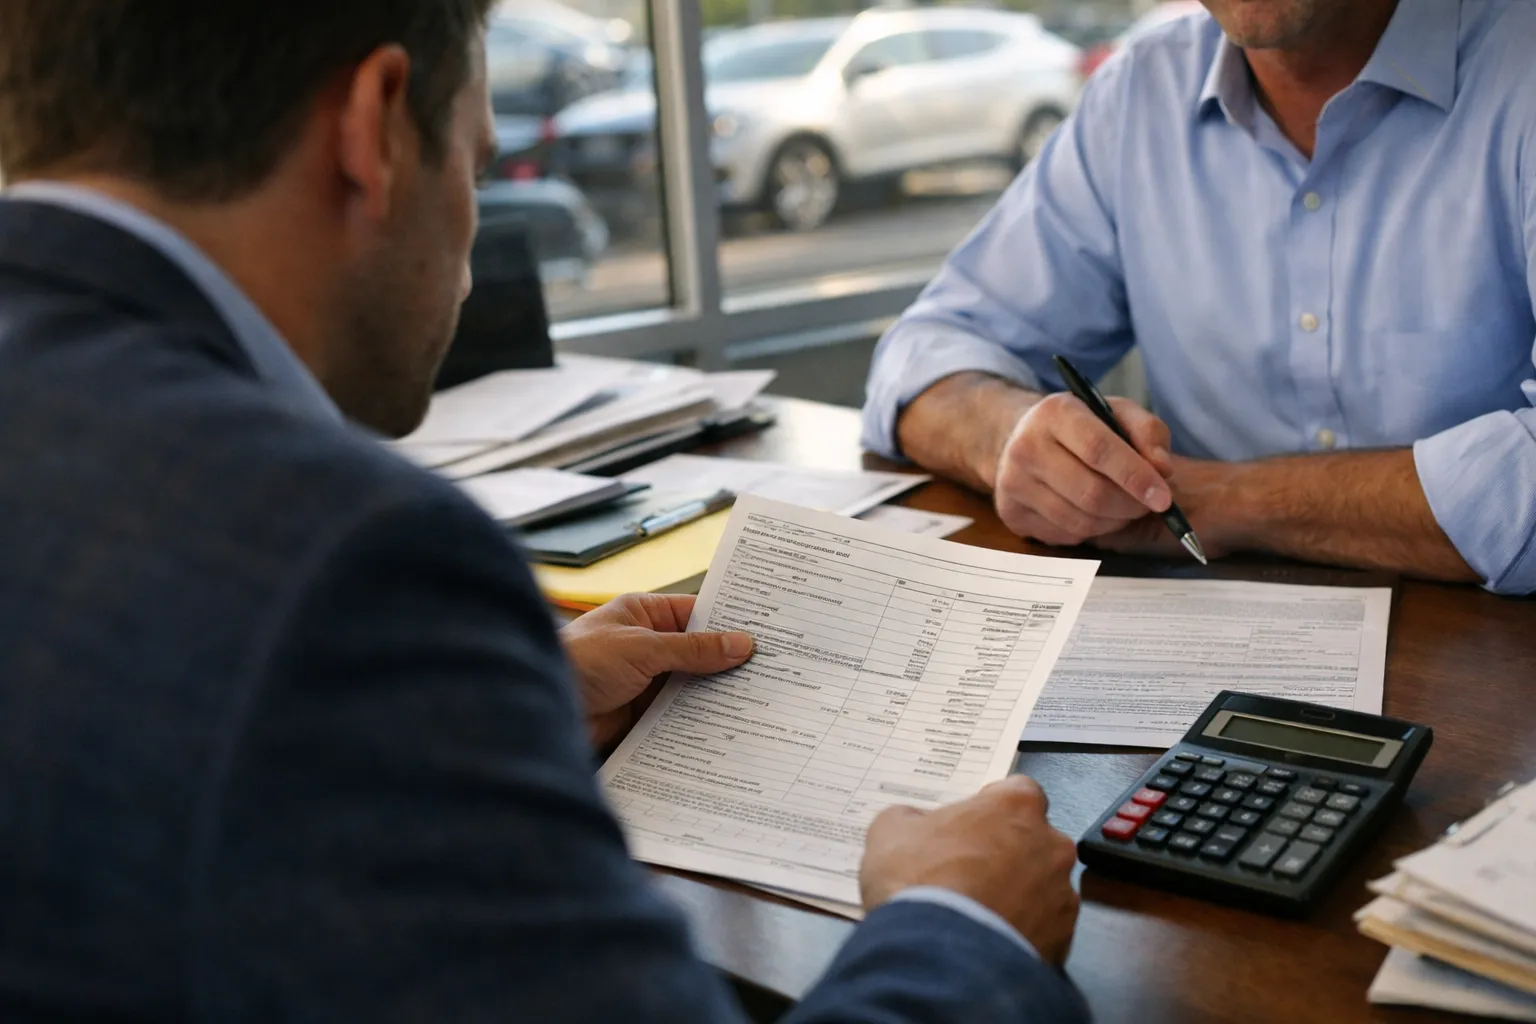
- Emailed, itemized buyer’s order or purchase agreement. Must show: vehicle price, each add‑on (one‑time and recurring) with individual prices, dealer fees, tax, title, registration, and the exact out‑the‑door total.
- Subscription disclosure sheet. For any monthly service, demand: monthly price, total cost over the financed term, cancellation policy (including any pro‑rated refunds), and whether the service transfers to a subsequent owner.
- Named‑lender verification. If financing is represented as “required” for a product, obtain a lender email or printout confirming the lender’s condition and contact information.
- Digital‑flow screenshots with timestamps and URLs. Save configurator pages showing advertised price, incentives, and pages where you consented to electronic deals.
- Explicit software/feature warranty statement. For complex driver‑assist or connected services, obtain a statement that specifies feature availability, transferability and update policy.
- Hard credit‑pull consent. Clear written consent before any hard inquiry; bring a pre‑approval to reduce surprise pulls and to spot markup attempts.
Impact: who should care most
All buyers should be vigilant, but the financial effect scales with vehicle price and feature set. On a $100,000 luxury SUV, recurring software subscriptions and a financed protection package can add several thousand dollars to the total cost of ownership. For short‑term leasers or frequent traders, non‑transferable subscriptions strip resale value and change the calculus of leasing vs. buying.
Reactions and what buyers can infer
Consumer advocates continue to press for national disclosure standards; dealer groups, including the National Automobile Dealers Association, emphasize operational complexity and consumer choice. The practical result: a marketplace divided between dealers and OEMs that voluntarily display full out‑the‑door pricing to win time‑sensitive buyers, and others that preserve traditional add‑on revenue streams. For discerning buyers, transparency is now a competitive advantage you can demand.
What’s next: what to watch through late 2026
- Litigation status of the CARS Rule. The rule remains stayed as appeals proceed; any court decision will rapidly change disclosure and opt‑in obligations.
- State regulatory activity. Expect additional guidance and enforcement by state attorneys general and consumer agencies targeting subscription disclosures and deceptive advertising.
- OEM and dealer pilots. Watch which national groups promote true out‑the‑door pricing and clear subscription terms — early adopters may set a new market norm.
FAQ
Is the FTC CARS Rule in effect as of June 24, 2026?
No. As of June 24, 2026 the CARS Rule remains stayed while litigation continues, so its specific national opt‑in and disclosure mandates are not yet enforceable as a standalone rule.
If the CARS Rule is paused, can dealers add fees without disclosure?
No. Dealers are still subject to the FTC Act, TILA/Regulation Z for financing, and state UDAP and motor‑vehicle laws. But what counts as adequate disclosure varies by state and by context, so insist on the written itemizations described above.
How do I handle subscription or software fees at signing?
Demand a subscription disclosure sheet showing monthly cost, total cost over the term, cancellation terms and transferability. If the dealer cannot confirm those items in writing, decline or negotiate removal.
Can I record conversations with the dealer?
Possibly. Recording laws vary by state—some require all‑party consent. If you plan to record, confirm your state’s law first or rely on written confirmations and emailed documents instead.
What single document should I insist on before signing?
An emailed, itemized buyer’s order or purchase agreement that shows the selling price, every add‑on (with whether each is recurring), taxes, title/registration, lender name (if any), and the exact out‑the‑door total.
The most refined purchase in 2026 is not merely about leather and finish; it’s about contractual clarity. Bring discipline to the transaction, and insist that every recurring cost is written, totaled and transferable — or walk away.