Introduction
This guide shows exactly how to verify a dealer’s out‑the‑door (OTD) price in June 2026. It’s for car‑buying enthusiasts, collectors, lease‑rotators, and anyone who treats the paperwork as seriously as the test drive. You’ll get a repeatable audit method: the documents to demand, the arithmetic to verify, the negotiation language that works, and updated checks for 2026 realities — more digital quoting, conditional EV incentives, and subscription‑style product billing. Read it before you sign anything.
Prerequisites / Context: what to know before you audit an OTD quote
Before you request or accept an OTD number, assemble these items. They lock the inputs so your verification is reliable.
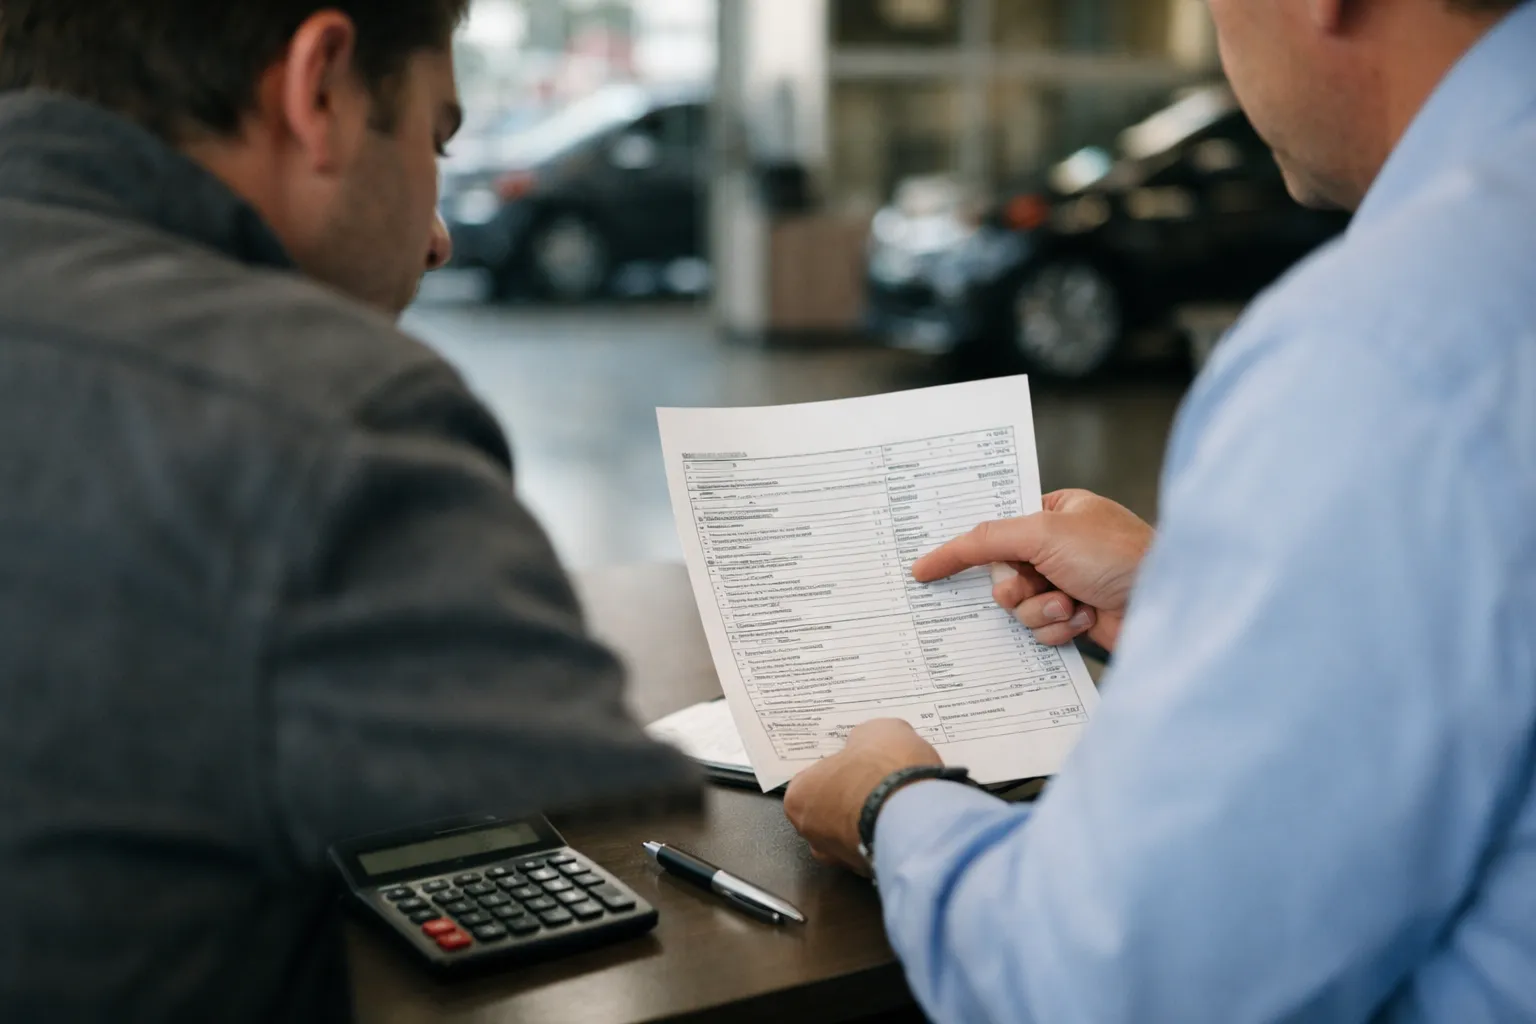
- Itemized buyer’s order (PDF or email). Do not accept a screenshot of a monthly payment or a terse “drive‑off” figure. The buyer’s order must list each line item.
- Your registration address (ZIP/county). Sales/use tax, local levies, and plate fees are location dependent.
- Trade‑in paperwork. Payoff statement, current registration, and any written appraisal or offer. Know your state’s trade‑in tax rules.
- Finance pre‑approval or lender proof. APR, term, and conditions — bring it to the dealer for leverage and to compare buy‑rates.
- Proof of incentive eligibility. Manufacturer bulletins, loyalty proof (registration/title), military/employer certificates. For EVs, plan to check the IRS clean vehicle credit guidance and ask whether the dealer will transfer the credit at point‑of‑sale.
- VIN and build information. The buyer’s order must match the exact VIN and factory build; mismatches are a red flag.
Why it matters: The OTD figure is an arithmetic result of many interdependent inputs. Lock the inputs first, then verify the math.
Step 1: Demand the correct document — a full, itemized buyer’s order
- Require a full buyer’s order that lists: vehicle sale price, each manufacturer rebate (by program name), dealer fees, accessories and protection products (itemized), taxable subtotal, taxes, DMV/title, and final OTD total.
- Refuse to negotiate on monthly payment alone. Monthly payments can be engineered by term changes, APR markups, or rolling costs into finance.
- Clarify financing dependency. If a rebate or sale price is conditional on dealer/captive financing, it must be stated plainly with the program name or code.
Practical indicator: A reliable worksheet separates taxable from non‑taxable items and shows the taxable basis. Without that line, you cannot verify taxes or rebates.
Step 2: Recast the quote into three buckets — the anti‑confusion filter
Rewrite every buyer’s order into three buckets to make padding obvious and focus negotiation.
- Bucket A — Vehicle price & incentives: MSRP, negotiated sale price, documented manufacturer rebates (program names), and dealer cash. For EVs, note whether the federal clean vehicle credit is being applied at sale or retained for the buyer’s tax return.
- Bucket B — Government & statutory costs: sales/use tax, title, registration, license plates, mandated emissions or inspection fees, and state EV surcharges where applicable.
- Bucket C — Dealer‑controlled items: doc fee, transportation/delivery, dealer add‑ons, protection plans, subscription activation fees for connected services, market adjustments and advertising fees.
Why it matters: Bucket B is largely fixed (but verify the rate). Bucket C is margin territory — where most last‑minute surprises live.
Step 3: Verify the vehicle price and equipment are correct
- Confirm VIN and exact trim on the worksheet match the car. Dealers sometimes substitute options or mislabel trims; insist on VIN match.
- Ask whether the sale price is before dealer‑installed accessories. Get a written confirmation on the buyer’s order.
- Request the Monroney sticker or factory build sheet. Use it to separate factory equipment from dealer add‑ons.
Luxury lens: A named, warrantied installer for paint protection film or bespoke interior trim is traceable value. A vague “appearance package — $1,600” is negotiable margin unless documented with supplier, scope and warranty.
Step 4: Audit incentives and rebates — demand program names and evidence
In 2026 incentives are more conditional and more frequently contingent on specific finance products, vehicle sourcing, or ownership history. Treat every rebate as provisional until documented.
- List each rebate by program name and source. Example: “Manufacturer Loyalty — Bulletin 2026‑05” or “Dealer Finance Cash — Captive Program Code X.” If the dealer supplies only “$3,000 rebate,” ask for the program code or bulletin URL.
- Confirm eligibility triggers. Loyalty often needs household registration; conquest requires competitor proof; finance cash may require use of a specific lender and term.
- For EVs: confirm point‑of‑sale transfer. Dealers must be enrolled with the IRS to transfer the clean vehicle credit at point‑of‑sale. Ask for the dealer’s enrollment confirmation and how they verified vehicle and buyer eligibility. If they don’t transfer it, you will claim the credit on your return subject to IRS rules.
- Require rebate disclosure in the buyer’s order. Do not sign for rebates you cannot document as eligible for today.
Why this matters: Ineligible or assumed incentives are the most common mid‑contract corrections buyers experience. Get the program name, the terms and a signed confirmation of eligibility before you finalize delivery.
Step 5: Verify taxes and the taxable basis numerically
- Confirm the combined tax rate for your registration address. Use your state revenue or DMV site to verify state + county + city rates before trusting the dealer’s math.
- Ask the dealer to show the taxable subtotal. Multiply it yourself and compare. The buyer’s order should clearly show the line the tax is applied to.
- If you have a trade‑in, verify trade tax rules in your state. Some states deduct trade value from taxable basis; others do not.
Illustrative example: Taxable subtotal $62,000 at 8.25% should yield $5,115 tax. If the buyer’s order shows $5,850, demand the calculator the dealer used and reconcile the discrepancy before signing.
Step 6: Decode fees — what’s legitimate, what’s padded, and what’s negotiable
Fees are the most common place a promising sale price becomes ordinary. Treat them like line items on a fine‑dining invoice: ask what each one covers and for proof of third‑party costs.
Document (doc) fee
- What it is: Administrative cost for paperwork and compliance.
- Reality: Some states cap it; others don’t. It can be a negotiated or flat dealer policy.
- Strategy: Ask if the doc fee is identical for all buyers and request an itemized description. If it varies by buyer, it’s fair game to negotiate.
Transportation / delivery / remote‑delivery fee
- What it is: Charges for moving a car between lots or delivering to your home. With concierge deliveries common in 2026, delivery fees have proliferated.
- Strategy: Confirm what the fee covers, whether it’s refundable on cancellation, and whether a third‑party invoice exists.
Subscription activation and connected services
- What it is: Activation fees for telematics, concierge, or OTA feature subscriptions; some dealers bill upfront for the first-year activation.
- Strategy: Insist the subscription charge be optional or clearly time‑limited and itemized. If the vehicle’s value depends on included services, require the contract terms and cancellation policy in writing.
Step 7: Treat add‑ons as optional until proven otherwise
- Identify every non‑government line item. VIN etching, ceramic coating, extended service contracts, GAP, wheel/tire protection, alarm subscriptions, appearance packages.
- Ask for a written answer: “Is this required to take delivery? If yes, required by whom — manufacturer, lender, or dealer?”
- If the dealer claims policy is the reason: request removal, a price offset, or a documented upgrade with named installer, scope and warranty.
Luxury note: High‑end buyers will pay for bespoke services when the value is transparent and the installer/warranty are named. That craftsmanship and traceable warranty matter; vague descriptions do not.
Step 8: If you finance, audit APR, buy‑rate and financed amount like an accountant
- Distinguish OTD total from amount financed. Amount financed = OTD minus down payment + rolled‑in negative equity or optional products.
- Get APR, term, lender name and buy‑rate in writing. If you have a competing pre‑approval, ask the dealer to disclose the buy‑rate and any reserve/markup they added.
- Verify payment math with an amortization calculator. If payments differ materially from computed figures, demand an explanation before you sign.
- Confirm cancellation/refund policy for rolled‑in products. Some products are cancellable with refunds; others are not. Ask before they are financed.
Pro tip: Present a printed or digital pre‑approval from your bank or credit union. Competing offers keep finance terms honest.
Step 9: Build a clean comparison table — choose the best verified deal, not the best story
When cross‑shopping, use a simple spreadsheet with these columns: VIN/stock, sale price (pre‑fees), total dealer fees, total dealer add‑ons, taxable subtotal, taxes, DMV/title/reg, OTD total, and finance terms (APR/term). Verify each cell with documentation. OTD total is the one true comparison; monthly payment is a marketing line.
New 2026 realities to watch — short, practical list
- Digital buyer’s orders and e‑signatures: Many dealers send signed PDFs before delivery. Make sure the final signed copy matches the most recent quote you approved; e‑signatures can lock in changes — read before signing.
- Subscription economy: Expect more line items for telematics or remote features billed as activation or multi‑year packages. Insist on itemization and a written cancellation policy.
- EV incentive complexity: Confirm dealer enrollment for IRS point‑of‑sale transfers and verify vehicle eligibility (MSRP caps, battery sourcing rules) via manufacturer bulletin or IRS guidance.
- Concierge and white‑glove delivery: These services are often charged as convenience fees. Demand proof of third‑party costs or negotiate them away.
Common mistakes that inflate your OTD price (June 2026 edition)
- Comparing monthly payments across different APRs/terms instead of comparing OTD totals.
- Assuming manufacturer or federal incentives apply without written proof — especially common with EV credits and regionally restricted offers.
- Missing subscription activation and multi‑year telematics fees hidden as “service activation.”
- Accepting delivery or convenience fees without proof of third‑party cost.
- Allowing protection products to be rolled into financing without confirming refundability and cancellation.
Pro tips: negotiate with precision and keep the tone civil
- Use “remove or offset” language. Example: “Please remove the $1,395 protection package or reduce the sale price by $1,395 so the OTD remains unchanged.” Clear and businesslike.
- Request two quotes. One with all dealer add‑ons and one stripped to essentials. It forces transparency and helps you assess value.
- Get the itemized buyer’s order before visiting or scheduling delivery. Digital quoting makes this easier; don’t accept surprises at signing.
- Preserve documentation. Save PDFs, emails, and screenshots. If numbers change, you can point to earlier quotes.
- Know when to walk away. The best leverage is readiness to purchase elsewhere; competitors and time pressure are your allies.
Common mistakes and quick recovery strategies
- Signed for a rebate you don’t qualify for: Do not sign any conditional rebate acceptance without evidence. If already signed, escalate immediately to the general manager and demand a corrected contract or documented proof of eligibility.
- Payment math that doesn’t add up: Ask for the calculator used to produce the payment schedule and reconcile with an independent amortization tool. Do not sign until resolved.
- Surprise subscription charges: Request written cancellation and refund terms. If the dealer pre‑activated a subscription, insist they remove the charge if you did not authorize activation.
FAQ
Can dealers apply the federal EV tax credit at the point of sale?
Some dealers can — but only if they’re enrolled with the IRS transfer program and have verified the vehicle and buyer meet eligibility rules. Ask the dealer for proof of enrollment and how they verified vehicle eligibility. If they won’t or can’t transfer the credit, you will claim it on your tax return subject to IRS rules.
What should I do if the buyer’s order shows a rebate I don’t qualify for?
Do not sign. Ask the dealer to remove the rebate or provide written evidence of your eligibility (program bulletin, dealer confirmation or lender documentation). If you’ve already signed and later discover ineligibility, insist on a corrected contract immediately — dealers can and do correct contracts, and you should not absorb that cost.
Are subscription, telematics and activation fees negotiable?
Yes. Treat them as optional until they’re documented and explicitly required by the manufacturer or lender. Insist on itemization, a defined term (for example, “first year included”), and a clear cancellation/refund policy if you change your mind.
Is the doc fee negotiable or fixed?
It depends on your state and the dealer. Some states cap doc fees; others do not. If the dealer insists it’s non‑negotiable, negotiate the sale price instead to preserve your target OTD total. Ask whether the fee is standard for all buyers and request an itemized explanation.
Quick sanity check for financed payments — what should I verify?
Confirm the amount financed, APR, term and lender in writing, then run the payment through a standard amortization calculator. If the payment shown differs materially from your calculation, ask for an immediate explanation and a corrected schedule before signing.
Final note: State laws and federal guidance change. Before finalizing an OTD, confirm tax rates with your state revenue agency, verify EV credit rules on the IRS website, and keep all quote documentation. In June 2026 the basics still win: demand itemized numbers, verify the taxable basis, and treat every non‑government line item as negotiable until proven otherwise. That discipline preserves both your time and your money.